Showing posts with label Market Trends. Show all posts

Sunday, March 10, 2013

MARKET TRENDS: Real estate markets strengthen


Nearly all twelve Federal Reserve districts reported modest to moderate growth in economic activity in the Fed's latest February Beige Book.
Residential real estate markets posted the strongest results, with impressive growth throughout nearly all the districts as home prices rose amid falling inventories across the country, the report said.
The Boston, Dallas, Kansas City, Minneapolis, San Francisco and St. Louis districts reported slight improvements.
Meanwhile, Philadelphia real estate continued to report low-end home prices as firm or rising or increasing slightly, while high-end home prices continued to fall.
Inventories also declined in nearly all districts, with Realtors in several districts concerned about the impact on future sales volume, the report noted.
Home construction increased in most districts, with the exception of the Kansas City District where it was reported as unchanged.
Additionally, several districts noted ongoing strength in multifamily construction. However, the Atlanta and Cleveland districts reported continued financing difficulties for builders.
Overall commercial real estate conditions were mixed or slightly improved in most districts, the

Saturday, March 9, 2013

MARKET TRENDS: Home prices finally returning to normal

After years of wild swings, the U.S. housing market is slowly returning to normal.

The latest forecast from Fiserv (FISV) Case-Shiller predicts home prices will increase by an average of 3.3% annually over the five years ending September, 2017.

"2012 was the first year since 1997 that the housing market has resembled something [close to] normal," said David Stiff, Fiserv's chief economist. "For the past 15 years, home price changes and sales volumes have either been boosted by a bubble mentality or crushed by crash psychology."

From 1998 until the housing bubble peaked in 2006, home prices grew by 5% or more a year. But once the bubble burst, home prices plunged, falling 30.5% through the end of September 2012.

It wasn't until late 2011 that markets started to stabilize, according to Stiff. Between September 2011 and September 2012, average U.S. home prices rose 3.6%. By then, 62% of the 384 metro areas Fiserv tracks reported rising home prices, up from just 12.5% of all markets during the same period a year earlier.

Many of the metro areas hit hardest by the housing bust recorded the biggest price gains

Friday, March 8, 2013

NEW DEVELOPMENT: 32-story complex planned for the Back Bay State picks developers for multiuse project over Pike

A Boston development team has won the right to build a towering $360 million hotel, residential, and retail complex on state-owned property in the city’s Back Bay, adding to a surge of ambitious building proposals in the area.

The Massachusetts Department of Transportation on Monday selected Samuels & Associates and Weiner Ventures to construct a 400-foot-high complex — about 32 stories — near the intersection of Massachusetts Avenue and Boylston Street.

The project, which still needs final approval from Boston regulators, would straddle the Massachusetts Turnpike and bring modern, glass buildings to what is now an empty, windswept corner of the Back Bay. The development would include two buildings with 230 residences, 270 hotel rooms, and 50,000 square feet of retail space.

“This project will make the area more walkable and active for residents, businesses, and visitors alike,” said Adam Weiner, a partner with Weiner Ventures. “It will reenergize the whole neighborhood.”

Related
View the proposed development (PDF)

The selection of Weiner and Samuels is the first step in a long, uncertain process to get the project built. In recent years, several developers have proposed construction of massive developments in air rights over the turnpike, only to see them fail or get delayed due to financial problems, community opposition, or permitting troubles.

Executives with both firms said they are optimistic because most of the project would be built around the turnpike, not directly over it, making it cheaper and less complicated to build than other air-rights developments.

Massachusetts transportation officials, who have been burned by prior air-rights projects, such as the failed Columbus Center, also struck a positive tone Monday.

“This will be the first air-rights project in over 30 years and we think it will be transformative,” said Dana Levenson, chief financial officer for the transportation department. “We’re very

Tuesday, March 5, 2013

SELLING YOUR HOME: Top 5 Mistakes Home Sellers Make


THE REAL ESTATE market may be in the doldrums, but that doesn't mean it's impossible to sell your home. Sellers just need to be savvy and not fall prey to common mistakes. Here are five missteps home sellers should avoid:
1. Asking Too Much
The single biggest mistake folks make is setting their asking price too high. In today's down market homeowners need to price conservatively or they risk turning off potential buyers, says Michael Corbett, author of "Ready, Set, Sold."
Figuring out how to set the price is tricky. Gone are the days when you can expect to sell your home for as much as your neighbor did just six months ago, according to the National Association of Realtors. So rather than looking at how much homes in your area sold for six to 12 months ago, compare prices for similar properties currently on the market. If you see a listing for a house that's sitting unsold for a few months, chances are the owners are asking too much and you'll want to set your price lower, says Corbett.
Watch our video for more advice on setting the right price.
2. Questioning the First Offer
Read our story here
The reality is that in any market a home's first offer is often its best, says Elaine Clayman, a real estate broker with Brown Harris Stevens. Typically, educated buyers will seize on a property they like with a competitive bid as soon as it comes onto the market, she says. Of course, given the glut of houses on the market, sellers should expect to receive some low-ball offers. Just don't assume that you'll get better bids the longer you hold out. As Clayman warns, the more time a home sits unsold, the greater chance a seller will have to reduce his price.
3. Failing to Respond to All Offers
What if you get an offer that's simply too low? Don't reject it outright. See if you can negotiate. First of all, you can't blame someone for testing the market after all, in today's market, many buyers are confident that they have the upper hand. Secondly, by entering into negotiations with one party, you'll gain leverage with other potential buyers, says Corbett. Most importantly, it allows you to tell brokers that your property is in play and sends a message that if someone is interested, then he better present a competitive bid quickly.
Just don't get cocky. During this process, it's crucial for sellers to set a realistic bottom-line price they're willing to take, even if it's several thousand dollars below asking, says Corbett.
Watch our video for more advice on negotiating.
4. Paying for a Home Stager
In a depressed market, it's more important than ever that your property stands out from the competition. But unless you're trying to sell a multimillion-dollar mansion, you don't need to pay a professional to stage your home. There are a number of free or inexpensive things you can do on your own to get your house into show condition. Most importantly, paint the walls. Nothing does more to brighten up a place, says Peter Comitini, a real estate broker with Corcoran Group. Next, he recommends getting rid of all the clutter, excess furniture and family knickknacks. Finally, make all the necessary repairs before your first open house. If a buyer sees a small problem, say, a leaky faucet, he's likely to wonder about larger issues like the furnace or roof.
Read our story here for more home improvements that pay off. Or watch our videofor more techniques on how to stage your home.
5. Picking the Wrong Buyer
Now more than ever, sellers need to select their buyers carefully. As we mentioned earlier, thanks to all the defaults in the subprime market, lenders are tightening their lending practices, making it more difficult for consumers to qualify for mortgages. So it's critical to find a buyer with a recent prequalification letter (issued no later than four to six weeks ago) for a loan.
Next, watch out for buyers who need to add contingencies to the contract, including a clause stating that the deal won't close until they sell their own home. A better bet is to look for cash-flush first-time home buyers or someone who has already unloaded his existing house. In a slowing market it's difficult to estimate how long it could take your buyer to find someone to purchase his dwelling, warns Brown Harris Stevens' Clayman. And if that property doesn't go for as much as he expected, that person may no longer be able to afford your agreed-upon price.This story was originally published on AOL on May 19, 2008.

Monday, March 4, 2013

BUYING A HOME: Boston Housing Shortage Daunting For Home Buyers

John and Melissa Smith are eager to sell their three-bedroom home in Waltham and buy something larger now that they have two children. But the starter home the Smiths purchased seven years ago — near the market’s peak — won’t command a high enough price to make a move feasible.

Ashley Krause and her partner, Kerri Scott, are interested in moving from Krause’s family condo in Roslindale to a single-family home, but so far they haven’t found anything enticing enough to justify jumping into the real estate fray.

Those are just two examples of why so many people in the region’s real estate industry — and especially potential home buyers — are asking the same question: Where are all the home sellers?

The number of homes for sale in Massachusetts is at an eight-year low, despite an increasing number of prospective buyers and a housing market that — overall — is on the mend. Some owners can’t afford to sell because they owe more than their properties are worth, while others aren’t yet convinced it’s the right time. The result is the demand for homes far outstrips the meager supply, an equation that threatens to hold back growth in a business crucial to the state’s economy.

“There is nothing on the market for me to want to buy to move into,’’ said Krause, a 31-year-old pharmacist who rents from her sister. “I’m afraid to put her condo up for sale and end up on the street.”

The situation differs dramatically from a few years ago, when the local housing market slowed to a glacial pace following the national subprime mortgage meltdown and tumbling home values. Then, real estate agents were practically begging for people to go house-hunting. Now, potential buyers are out in droves — motivated by low interest rates and renewed confidence in the economy — and it’s homeowners who are on the sidelines.

In Massachusetts, the number of single-family homes for sale fell to 18,329 at the end of January, 27.3 percent fewer than during that month last year and the steepest year-over-year fall in almost a decade, the Massachusetts Association of Realtors reported this week.

The tight market has prompted robust competition in some of the Boston-area’s more popular neighborhoods, prompting bidding wars and price inflation, real estate agents say. Statewide, homes are selling more quickly than a year ago. Single-family homes remained on the market for an average 114 days in January compared with 128 days in January 2012, the realtors group said.

“More buyers are competing for fewer homes and we are shifting to a stronger seller’s market,’’ said Sam Schneiderman, president of the Massachusetts Association of Buyers Agents.

Concerned the lack of properties for sale could hurt the all-important spring selling season, real estate agents are cold-calling potential sellers, penning handwritten notes, and launching seminars to attract new business. Their universal message — demand is high, supply is low; it’s time to list. “Everybody in the world is trying to reach sellers,” said Alex Coon, a Boston-area manager of the online brokerage firm Redfin.com. “Home-buying classes are brimming over. Anywhere we can find a seller, we are trying to reach them.”

It’s not just that sellers are sparse — it’s that buyers are quickly snatching up attractive homes almost as soon as they are put up for sale. Last year, the Massachusetts housing market began to build momentum. Statewide, 46,887 single-family homes were sold, the most since 2006, according to Warren Group, a Boston company that tracks local real estate. The buzz of activity carried over into January, with sales 10 percent higher than the same month in 2012, Warren Group said.

But some worry that if sellers don’t soon start showing up in greater numbers, the upward sales trajectory will falter.

“If we don’t have the inventory to sell, we won’t be able to continue” improving, said Kimberly Allard-Moccia, the president of the Massachusetts Association of Realtors and broker-owner of Century 21 Professionals in Braintree.

Currently, there is a 4.7-month supply of single-family homes for sale, according to the Massachusetts Association of Realtors. A balanced market has about 6 months worth of supply according to the Washington, D.C.-based, National Association of Realtors. Anything less tips the market in favor of sellers.

Eric Belsky, managing director of the Joint Center for Housing Studies at Harvard University, said the relative lack of homes for sale suggests many interested home buyers are coming from outside the area, or are local first-time home buyers or investors. Otherwise, he said, buyers would be selling their existing properties — leaving local inventory relatively unaffected. Thin inventory puts upward pressure on prices, Belsky said, but it’s still unclear whether the increases are enough to get more people into the market. “It’s an open question,” he said.

John Ranco, a senior sales associate for Hammond Residential Real Estate in Boston’s South End, said many homeowners who couldn’t sell their properties during the recession turned to renting, which currently can be a lucrative source of income in the city. In addition, he said, more Boston residents also have decided to stay in their current homes, lessening the opportunities for newcomers.

Also, thousands of homeowners are still plagued by a recession hangover. Despite the recent upturn, Boston-area home values are down nearly 16 percent since their peak in 2005. So many homeowners owe more to lenders than their properties could fetch for sale.

Other potential sellers are simply doing what some do every year — waiting for the snow to clear. “No one likes muddy boots tramping through their houses,’’ Ranco said.

Meanwhile, real estate agents are becoming more aggressive about targeting sellers.

Steve Mehigan, manager of the Coldwell Banker Residential Brokerage office in Waltham, said his agents are reaching out to homeowners who unsuccessfully tried to sell their properties with other real estate offices. Sometimes his agents will show up at a homeowner’s door to let them know multiple buyers are interested in their property.

“Our buyer appetite is absolutely voracious,” Mehigan said.

Brian Montgomery, a buyer’s agent with Charlesgate Realty Group in Boston, was so frustrated by his inability to find suitable homes for his clients that he recently published a blog post titled: “Desperately seeking sellers.” It included a wish list of nearly two dozen Boston-area homes his clients would like to buy.

Montgomery listed properties in Brookline, Boston, and Cambridge. “We’re hoping that by publishing this list, an owner may wake up from their amnesia,” he wrote, “and realize they actually want to sell their property!”

For Emily Glass, 33, of Arlington, it’s not amnesia that is keeping her in her Arlington condominium. She just doesn’t see any place better. “There is really nothing available,” Glass said.

Krause, the Roslindale condo dweller, said properties she’s toured over the last few months are either too small or lack a yard. But she also gets the irony of her situation — while she searches for the perfect home, her family’s condo remains off the market and out of play for some other prospective buyer.

“Right now, I need some people like me to let their places go,” she said.

Saturday, March 2, 2013

SELLING YOUR HOME: 5 Reason you should List your home Now


Many homeowners are waiting until the Spring ‘buying season’ to list their homes for sale. Here are five reasons why that might not make sense this year:

1.) Demand Is High

Homes are selling at a pace not seen since 2007. The most recent Existing Home Sales Report by the National Association of Realtors (NAR) showed that annual sales in 2012 increased 9.2% over 2011. There are buyers out there right now and they are serious about purchasing.

2.) Supply Is Low

The monthly supply of houses for sale is at its lowest point (4.4 months) since May of 2005. The current month’s supply is down 21.6% from the same time last year. Historically, inventory increases dramatically in the spring. Selling now when demand is high and supply is low may garner you your best price.

3.) New Construction Is Coming Back

Over the last several years, most homeowners selling their home did not have to compete with a new construction project around the block. As the market is recovering, more and more builders are jumping back in. These ‘shiny’ new homes will again become competition as they are an attractive alternative to many purchasers.

4.) Interest Rates Are Projected to Inch Up

The Mortgage Bankers’ Association has projected mortgage interest rates will inch up approximately one full point in 2013. Whether you are moving up or moving down, your housing expense will be more a year from now if a mortgage is necessary to purchase your next home.

5.) Timelines Will Be Shorter

The dramatic increase in transactions caused many challenges to the process of buying or selling a home in 2012. We waited for inspections, dealt with last minute appraisals and prayed that the bank didn’t ask for ‘just one more piece of paper’ before issuing a commitment on the mortgage. There are fewer transactions this time of year. That means that timetables on each component of the home buying process will be friendlier for those involved in transactions over the next 90 days.

Thursday, February 28, 2013

MARKET TRENDS: Americans Increasingly Optimistic About Housing


While the greater American economy has been slowly lifting itself from the recession, the housing market has been particularly slow to turn around. Fortunately, 2012 was an exceptionally positive year for the housing market, and the property sector has become one of the fastest-growing segments of the American economy. In fact, the housing market’s rebound has become so assertive that certain reports indicate housing’s advance has become a growth engine for the economy as a whole. One of the accumulated positives of all this, it seems, is that the American public has become increasingly confident about the housing market’s future as well.
According to new reporting from Bloomberg, Americans are overwhelmingly certain that the property sector will undergo substantive improvement by the close of 2013. As the article notes, those polled believe that the housing market will improve within the next year by a three-to-one margin. While 31% of those polled expressed ambivalence about the housing market’s prospects, a full 50% believe the housing market would improve over the next twelve month against only 16% of those who foresaw negative returns for housing. With metrics derived from a Bloomberg National Poll, statistical analysis points towards a sea change in the public’s attitudes towards the real estate sector.
It’s naturally pleasing to hear that consumer confidence is returning in a big way. However, do the harder statistics validate this newfound positivity? As the Bloomberg report notes, the Commerce Department’s figures for new construction are outstanding. January returned the highest volume of initiated building projects since July 2008, with homebuilders beginning work on a sum 613,000 single-family homes. Housing values have also been rising substantively as well, with one of 2012’s greatest economic victories being the price recovery of large swaths of American property. As I noted in a previous post, much of this can be credited to the rapid purchase of otherwise neglected property working wonders for the supply-demand equation.
Theses are all constructive developments, especially considering that housing’s bubble bursting was held as the epicenter of the financial crisis. Many Americans felt rightly burned

Wednesday, February 27, 2013

SELLING YOUR HOME: Is There a Window of Opportunity for Sellers Right Now?


One of the most interesting revelations of the latestNational Association of Realtors (NAR) Existing Home Sales Report is the shortage of housing inventory being reported throughout much of the country. At the same time, buyer demand is dramatically up over last year.  Here are some key points:
  • Total housing inventory at the end of January fell 4.9 percent to 1.74 million existing homes available for sale, which represents a 4.2-month supply at the current sales pace.
  • This represents the lowest housing supply since April 2005 when it was also 4.2 months.
  • Listed inventory is 25.3 percent below a year ago when there was a 6.2-month supply.
  • Raw unsold inventory is at the lowest level since December 1999 when there were 1.71 million homes on the market.

What Does This Mean if You Are Selling a Home?

The price of anything is determined by supply and demand. According to NAR’s report, inventory is at its lowest level since the real estate boom eight years ago. At the same time, demand is up. Lawrence Yun, NAR chief economist, reveals:
“Buyer traffic is continuing to pick up, while seller traffic is holding steady. In fact, buyer traffic is 40 percent above a year ago, so there is plenty of demand but insufficient inventory to improve sales more strongly. We’ve transitioned into a seller’s market in much of the country.”
Does that mean you should sell your house now? Or should you wait to see if prices increase? Nobody knows for sure. However, some feel that there may be a pent-up inventory about to come to the market because, as prices increase, it will free up some sellers who have been locked in a negative equity situation (where the house is worth less than the remaining mortgage).
The Zillow Negative Equity Forecast predicts: 
“The negative equity rate among all homeowners with a mortgage will fall to at least 25.5

Tuesday, February 26, 2013

Survey: Single-Family Renters More Likely to Stay Longer


Renters who opt for single-family homes over apartments are more likely to live in those homes for five years or longer and more interested in ultimately becoming a homeowner, according to a study released Monday.
Some 26% of single-family-home renters said they planned to live in their current rental for five years or more, compared with 22% for renters in multifamily buildings. Three out of every five single-family renters also said they planned to become a homeowner within five years, compared with just 44% of apartment renters.
More than 14 million renters live in single-family homes in the U.S., but over the past year the sector has received much more attention from private-equity funds and other institutional investors looking to build large pools of rental homes by purchasing foreclosures and other distressed properties at fire-sale prices.
While some critics have questioned the ability of these firms to effectively manage hundreds or thousands of single-family homes scattered across a city, the lower turnover of single-family tenants could help reduce costs for landlords.
The survey, conducted by ORC International for Premier Property Management, also found that a majority of apartment and single-family renters indicated that they rent because they

Monday, February 25, 2013

MARKET TRENDS: Six Reasons Housing Inventory Keeps Declining


Home sales in December dropped by 1% from November, the National Association of Realtors reported on Tuesday, but still stood nearly 13% above the levels of one year ago. That means home sales have risen from the year-ago month for 18 straight months.
For 2012 as a whole, sales were up 9% to 4.65 million units, the highest annual total since 2007.
Prices, meanwhile, are picking up because the number of homes for sale continues to drop despite the sales volume gains. The number of homes for sale fell to 1.82 million at the end of 2012, an 8.5% drop from November and a 21.6% decline from one year earlier, the Realtors’ group said on Tuesday.
Here’s a breakdown of why inventory has continued to drop this year:
Many homeowners are underwater: More than 10 million homeowners owe more on their mortgage than their homes are worth, according to CoreLogic Inc. CLGX +0.61% That pencils out to around 22% of homeowners with a mortgage, or 15% of all homeowners (since not every homeowner has a mortgage). Underwater owners aren’t likely to sell unless they need to move due to changing life (marriage, divorce) or financial circumstances, and they’ll take a hit on their credit for pursuing a short sale, where the bank allows the home to sell for less than the amount owed.Data from CoreLogic show that inventory has been the most constrained in housing markets where there’s the largest concentration of underwater borrowers.
Others don’t have enough equity to “trade up”: Another 10 million homeowners have less than 20% equity in their current residence, meaning they can’t easily “trade up” to their

Sunday, February 24, 2013

BUYING A HOME: Don't Let House-Hunting Break Your Heart


This time of year love is on the minds of many. For those who are house-hunting, it can be a whirlwind romance that's hot from the minute you see the home's curb appeal. But don't let the seduction of a good-looking landscape make you want to tie the knot without a bit of courtship.

Keeping these terms clearly defined and always on your mind will help you make smart choices even when some areas of the home tug at your heartstrings and say "buy me!".House-hunting for the "perfect" home in many ways is like looking for that perfect romance - very seldom does everything about your proposed mate match your desires. Things you love at first may later get on your nerves and become what you don't like so much later on. Does that mean the house is wrong for you? Not necessarily. It could be, but if you understand your tolerance level–what's most important to you in a home, and what you can't deal with at all - you are less likely to want to buy the wrong home.

House-hunting should be like dating. Take your time. Understand the critical must-haves, the not-so-important-but-I-kind-of-want-it, and the no-way, not-going-to-happen-in-this-lifetime.
One thing you can do to help streamline the process is to start making a list about the things you like about your current home. If you're renting, there may be features about the home, apartment, or planned-living development that you want to find again in the neighborhood where you're going to buy your home.

For instance, you might want a gated community or a townhouse that has certain luxury amenities. Moving to an isolated home that doesn't have the same type of amenities could be a real turn-off. Also, it might mean you have to pay more to get those same amenities that used to

Saturday, February 23, 2013

BUYING A HOME: Seasonal Flip-Flop Hallmarks Housing Recovery, Tough Times For First-Time Buyers


Just as home price gains are moving up against the traditional seasonal grain, inventories are going down at a time when they typically turn up.

A new report by Movoto.comreveals the housing inventory is down to its lowest point in three years.And that's bad news for homebuyers, especially first-timerstrying to take the plunge.
Across Movoto's 34-city tracking area, inventories of homes for sale in January dropped to 88,000, down 19 percent from December and 47 percent off the 2010 peak.

Meanwhile the monthly list price per square foot increased from $169 in December to $173 in January, $155 a year ago and $162 two years ago.
By Movoto's measure, homes on the market today are more expensive they they've been for the past two years.

Graphs by Movoto Real Estate

Among the top 10 major metros with the greatest year-over-year drop in inventories, 7 are in California.

The top 10 cities in Movoto's coverage area with the greatest decline in homes for sale, along with the decline by percentage, are:
Sacramento - 75.11 percent
Oakland - 66.77 percent
San Francisco - 61.41 percent
Long Beach - 56.19 percent
San Diego - 49.34 percent
Los Angeles - 48.68 percent
Fresno - 47.62 percent
Portland - 43.18 percent
Denver - 39.02 percent
Houston - 35.02 percent

Movoto says inventories are inadequate for a host of reasons and those reasons are squeezing first-time home buyers out of the market.

• Equity is on empty - With insufficient equity to sell homes at a profit, homeowners are sitting tight. Only those who are struggling and unable to get a workout are forced to sell - at a loss. Until the market returns sufficient equity to these homeowners, they are going nowhere fast.

• Catch 22 - Homeowners who can sell at a profit are afraid they won't be able to purchase a decent move-up, -over, or -down home.

"Remember standing around at the high school dance wondering who's going to be first to ask

Sunday, February 17, 2013

BOSTON HOUSING NEWS: Residential tower pitched for the Fenway

For years, the gritty retail building at Brookline Avenue and Boylston Street has remained a bystander in the Fenway’s revitalization.

Not anymore.

Developer Samuels & Associates proposes building a 22-story residential tower on the property that would contain 320 residences and a two-story retail base with several new shops and restaurants.

The project, to be called The Point, would result in a modern masonry and glass tower on the triangular lot currently occupied by a D’Angelo sub shop and other businesses. Samuels filed plans for the project Friday with the Boston Redevelopment Authority, kicking off a monthslong review.


The building’s construction would continue a decadelong remake of the Fenway portion of Boylston Street, where Samuels and other developers have already built hundreds of new residences, restaurants, and retail shops.

“This counts as among the most exciting of our projects in the Fenway,” said Peter Sougarides, a Samuels & Associates executive. “In the almost 15 years that we have been working with the neighborhood, this property has always been thought of as a gateway into the Fenway and a key element of the redevelopment of Boylston Street.”

Samuels is currently building the nearby Fenway Triangle project at the corner of Boylston and Kilmarnock streets. That $325 million project will result in new offices, 172 residences, a Target, and several smaller retail shops and restaurants.

Designed by the architecture firm Arquitectonica, The Point would be the most visually striking of the buildings Samuels has developed so far. A rendering shows a wedge-shaped glass tower rising above a two-story base with restaurants and stores.

The windows on its north face would be layered so it looks like a series of glass doors are sliding into one another. In its filing with the city, Samuels said the building is meant to shake up

Tuesday, February 12, 2013

THE ECONOMY: Big money betting big on housing

Hedge funds and private equity firms have been rushing in to buy up companies and assets in every part of the housing supply chain, including undeveloped land, homebuilders, foreclosed homes, and building parts manufacturers.

One of the most notable moves is coming from hedge fund manager John Paulson, best known for his big (and lucrative) bets against subprime mortgages in 2006 and 2007.

Now, he's turned his attention to snapping up undeveloped land in areas hardest hit by the housing crisis. "Land is the accordion in the home building equation," said Michael Barr, who runs Paulson's real estate investments. "It falls the most in a downturn, but also rises the most in an upturn."

Over the past two years, Paulson & Co has bought up enough land in California, Arizona and Nevada to build up to 25,000 homes and is aggressively scouting for more, according to Barr.

Private equity firms are also getting in on the game.
Blackstone Group (BX) spent $2.7 billion last year to buy 17,000 single family homes, post-foreclosure, around the United States and plans to continue ramping up those efforts in 2013.
Pine River Capital Management took real estate investment trust Silver Bay Realty Trust (SBY) public in December. Silver Bay, which acquires, renovates, leases and manages single family homes, has already purchased more than 2,500 homes in areas hard hit by the housing crisis. In a recent SEC filing, Silver Bay said that it plans to purchase 3,100 more homes.

And in a sign of investors' growing appetite for a piece of the housing market, shares of publicly traded homebuilders have been soaring. PulteGroup (PHM), KB Home (KBH), and Lennar (LEN) are all trading near 52-week highs. Pulte's shares have more than doubled over the past year, while the KB Home and Lennar's shares have nearly doubled.

And for the first time since 2004, homebuilders are testing the IPO waters.

Tri Pointe Homes (TPH), which builds single family homes in California and Colorado raised

Monday, February 11, 2013

MARKET TRENDS: Impacts Of The Improving Housing Market

A lot of people are clamoring about the improving housing market. Many wonder if we have really turned the corner and how much better it will get. Also, what impact will it make?

Chief economist, Anthony Chan, for private wealth management at J.P. Morgan in New York, as reported by Business Observer, said, "Things are getting better because housing is getting better."

The rising housing prices ignite a sense of confidence in the economy and lead to greater spending. What this means is that there is great opportunity for sellers.

One group in particular is the "boomerang buyers". That's the term being used for those homeowners who lost their home to a short sale or foreclosure in the recent past and now are shopping for another home to buy.

However, the guidelines for these buyers are strict. It's likely they have to have at least 20 percent deposit and wait at least two years after the foreclosure before they can buy again. It's unlikely that high-risk loans will be available to this group.

Sellers are noting the improving housing market and anticipating an even better year. Part of that is not only due to rising home prices but also less inventory. In December, 1.82 million homes were listed for sale according to the National Association of Realtors, down 22 percent from a year ago. The supply hasn't been this low since 2005.

This may seem like all good news, at least for sellers, but if home prices rise due to a

Saturday, February 9, 2013

MARKET TRENDS:L Prices are up, but homes are in short supply


The supply of homes for sale has been shrinking for six months and shows no improvement so far in January — a bad sign for buyers.
Listings of existing homes for sale were down 14% year-over-year in the first two weeks of January, according to Realtor.com, which tracks 146 markets nationwide.
In Phoenix, where prices were up 24% in November from a year earlier, new listings through the first three weeks of January hit their lowest level in 13 years, says Mike Orr, real estate expert at the W.P. Carey School of Business at Arizona State University.
That's bad news for buyers, and it means "prices need to go up more" to bring more sellers to market, Orr says.
Nationwide, the supply of existing homes for sale fell to 4.4 months in December, based on the current monthly sales pace, says the National Association of Realtors. That's the lowest level in more than seven years. A six-month supply is generally considered balanced between buyers and sellers.
Home prices in November were 7.4% higher on average than a year earlier, according to CoreLogic. Real estate experts had expected that rising prices would spur more sellers trapped by years of falling prices.
Instead, January's listing data "is the same sad story," says Glenn Kelman, CEO of online brokerage Redfin. If sellers don't have to sell, "they're holding on, thinking they'll wait for prices to go up even more."
Redfin's data, covering 19 major markets mostly in the West, shows new listings down 29% the first two weeks of January vs. last year.
Scarce sellers aren't the only driver of shrinking supplies. There are fewer distressed properties for sale. Foreclosure sales were down 7% through the first nine months of last year from the same period in 2011, RealtyTrac says.
Meanwhile, demand is up. Existing home sales were up 9.2% last year, NAR's preliminary data show. New-home sales rose almost 20% in 2012, the government

Friday, February 8, 2013

THE ECONOMY: Tech sector spurs Mass. growth as US economy contracts


No one is calling it a return to boom times, but the state’s economy grew modestly in the ­final three months of 2012, even as the US economy unexpectedly contracted slightly, the University of Massachusetts reported Wednesday.
The contrast offered further evidence the state is rebounding from the recession at a more robust pace than the nation as a whole, largely on the strength of its technology industries.
“This appears to be a slow quarter, but the Massachusetts economy is growing still,” said Alan Clayton-Matthews, a Northeastern University economist and author of the report. “And growth is going to pick up.”
The state’s economy grew at a 1 percent annual rate in the fourth quarter, while the Commerce Department said the US economy shrunk at an annual rate of one-tenth of a percent, largely because of a pullback in government spending.
The state growth rates were reported in MassBenchmarks, an economic journal published by UMass and the Federal Reserve Bank of Boston. The decline in US economic growth was the first contraction since the first half of 2009, according to the Commerce Department.Over all of 2012, the Massachusetts economy grew 2.1 percent, compared with 1.5 percent nationally, according to UMass. The state also put people back to work at a faster rate — employment grew by 1.6 percent last year, compared with 1.4 percent nationally. Those figures could change, however, as revisions to the data are made in coming weeks by statistical agencies.
The report put a damper on the recent rally in US stocks, which retreated from five-year highs. The Dow Jones industrial average fell 44 points, or 0.32 percent, to 13,910.42, while the broader Standard & Poor’s 500 index fell 5.88 points, or 0.39 percent, to 1,501.96. The technology heavy Nasdaq lost 11.35 points, or 0.36 percent, to close at 3,142.31.
Economists said the contraction was not the harbinger of another US recession. But Federal Reserve policy makers, meeting in Washington on Wednesday, acknowledged in a statement that the economy had slowed in recent months as a result of Hurricane Sandy and other temporary factors. The Fed said it would maintain its policies to stimulate the economy and keep long- and short-term interest rates low.
Still, the decline surprised many analysts, who had forecast that the national economy grew at the end of last year, albeit weakly. Uncertainty about whether Congress would avoid a scheduled combination of tax increases and deep spending cuts — and potential recession

Wednesday, February 6, 2013

MARKET TRENDS: Housing market strengthening in US, around Boston


Home values in the Boston area rose by 2.3 percent in November compared with the same month in 2011, according to data released Tuesday by the S&P/Case-Shiller Home Price Indices, which is widely considered a reliable measure of the housing market.
Nationwide, the improvement was more pronounced, with prices increasing by 5.5 percent in the 20 metropolitan areas tracked by Case-Shiller. Unlike some other housing barometers, the index is based on repeat home sales, which many industry analysts consider a more accurate way to gauge the market.
The numbers add to a growing bundle of economic news showing the country’s long-suffering housing industry is on the rebound.
David M. Blitzer, chairman of the index committee at the S&P Dow Jones Indices, said the increase in sales and values provides further evidence the housing market is helping to jump-start the US economy.
But Blizter cautioned US home values are not likely to continue to rise at such a brisk pace. Normally, he said, values rise a bit faster than the rate of inflation.
“We are on the rebound and at some point the rise in prices will flatten out a little bit,” he

Monday, February 4, 2013

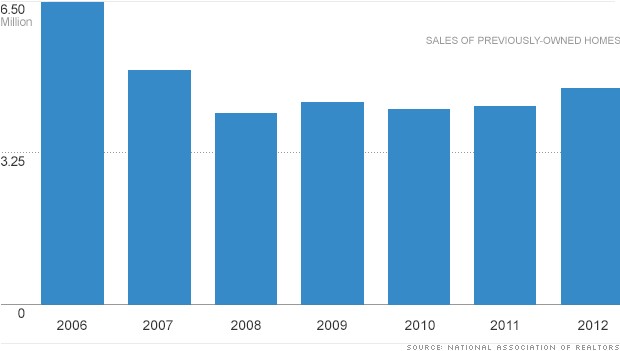
MARKET TRENDS: 2012 home sales: Best in 5 years

Steady December home sales capped the best year for the U.S. real estate market in five years, according to an industry trade group report Tuesday.


The National Association of Realtors said that December sales of previously-owned homes came in just slightly below November's sales pace, but up 12.8% from a year ago. That brought full-year sales to 4.65 million, up 9% from 2011 and the best year for home sales since 2007, when there were 5 million homes sold just before the start of the recession.

Sales are being helped by a combination of strong market fundamentals -- near record low mortgage rates, lower unemployment and a rebound in home prices, all of which are bringing in buyers into the market who had been waiting for it to hit bottom. The mortgage rates and years of depressed home prices have also combined to create the most affordable housing market on record, according to the Realtors group.
And the Realtors are predicting strong sales should continue into 2013 and beyond. It has a