
Monday, June 7, 2010

LOCAL NEWS: What a bigger convention center could mean to Boston
James Rooney wants to make Boston one of the nation’s premiere convention destinations. As executive director of the Massachusetts Convention Center Authority, he is proposing to accomplish that through a dramatic expansion of the six-year-old Boston Convention and Exhibition Center. He sat down recently with reporter Casey Ross to discuss the project and how to persuade a skeptical public to pay for it.
 That speaks to the question of whether we should be satisfied with not just the convention operation, but Boston’s role as a globally significant destination. In my view, Boston has a great deal of potential to be a meeting city in a new world economy, and part of that means hosting the most significant thought leaders, assemblies, conventions, and meetings in our core industries, be that life sciences, academic, or (information) technology.
Those are the underpinnings of our economy. We should be a leader in hosting groups that want to talk about those things. We don’t have the capacity to do that on the scale that we could.
Why isn’t the existing facility big enough?
It is the largest building in New England; it’s a total of 2.1 million square feet of built space and over a half-million square feet of exhibit space; it is longer on its side than the Empire State building is tall. It is huge. But that being said, it’s only the 23d-largest convention center in North America. Chicago, for example, has a facility that is five times as large as the BCEC. They are able to host multiple conventions at once, which we can’t do.
Is there enough space around the convention center for the expansion you envision? (Rooney has previously outlined a new 400,000-square-foot hall, a 5,000-seat auditorium, a 75,000-square-foot ballroom, and a 1,000-room hotel.)
When we acquired the land to build the BCEC, we assembled 62 acres, and we’ve used about 40. So we have a little over 20 acres. The hotel becomes a little trickier because two of the sites are above highway structures, so they would come at a premium to build. There are other sites on solid ground that don’t have that premium, and we’ll have to see whether there is a trade-off in the cost of construction versus site optimization.
Why should people support this?
It starts with jobs. This is one of the biggest and boldest development plans under discussion right now. There are a lot of people in the building trades out of work who would get jobs building this development. There are thousands of permanent jobs in the hospitality industry associated with conventions, and there are broader economic impacts generated by what conventions bring — hotel room nights, spending at restaurants, spending on entertainment. But there’s a more macroeconomic picture here, which is maintaining Boston’s leadership role in hosting meetings of key industries, and you can only accomplish that if you have the infrastructure.
What else is needed to support the BCEC’s growth?
The most critical component is additional hotel rooms. There are 1,700 hotel rooms within walking distance of the BCEC. For a big convention, we may be able to acquire for them 1,000 or 1,200 rooms. Competitor cities have an average of 8,000 rooms within walking distance of their conventions centers. So that means we’re busing people all over the city. That creates a competitive disadvantage because of the added expense in Boston that doesn’t exist elsewhere. And it’s an inconvenience for attendees. We need today 4,000 rooms; if we expand, we’ll need 6,000 rooms.
Those are the underpinnings of our economy. We should be a leader in hosting groups that want to talk about those things. We don’t have the capacity to do that on the scale that we could.
Why isn’t the existing facility big enough?
It is the largest building in New England; it’s a total of 2.1 million square feet of built space and over a half-million square feet of exhibit space; it is longer on its side than the Empire State building is tall. It is huge. But that being said, it’s only the 23d-largest convention center in North America. Chicago, for example, has a facility that is five times as large as the BCEC. They are able to host multiple conventions at once, which we can’t do.
Is there enough space around the convention center for the expansion you envision? (Rooney has previously outlined a new 400,000-square-foot hall, a 5,000-seat auditorium, a 75,000-square-foot ballroom, and a 1,000-room hotel.)
When we acquired the land to build the BCEC, we assembled 62 acres, and we’ve used about 40. So we have a little over 20 acres. The hotel becomes a little trickier because two of the sites are above highway structures, so they would come at a premium to build. There are other sites on solid ground that don’t have that premium, and we’ll have to see whether there is a trade-off in the cost of construction versus site optimization.
Why should people support this?
It starts with jobs. This is one of the biggest and boldest development plans under discussion right now. There are a lot of people in the building trades out of work who would get jobs building this development. There are thousands of permanent jobs in the hospitality industry associated with conventions, and there are broader economic impacts generated by what conventions bring — hotel room nights, spending at restaurants, spending on entertainment. But there’s a more macroeconomic picture here, which is maintaining Boston’s leadership role in hosting meetings of key industries, and you can only accomplish that if you have the infrastructure.
What else is needed to support the BCEC’s growth?
The most critical component is additional hotel rooms. There are 1,700 hotel rooms within walking distance of the BCEC. For a big convention, we may be able to acquire for them 1,000 or 1,200 rooms. Competitor cities have an average of 8,000 rooms within walking distance of their conventions centers. So that means we’re busing people all over the city. That creates a competitive disadvantage because of the added expense in Boston that doesn’t exist elsewhere. And it’s an inconvenience for attendees. We need today 4,000 rooms; if we expand, we’ll need 6,000 rooms.
Saturday, June 5, 2010
MORTGAGE & Finance: Mortgage rates near record low again
WASHINGTON — Turmoil in the stock market and the European debt crisis are making life easier for American home buyers and families looking to refinance: Mortgage rates are inching closer to a record low.
The window of opportunity may close soon. Home loan rates will rise if investors grow more confident and shift money out of the safety of government bonds, which influence mortgage rates.
For now, though, rates are tantalizingly low. The average 30-year, fixed-rate loan sank to 4.78 percent this week, the lowest this year and barely above the record of 4.71 percent set in December. And 15-year loans are at their lowest rates in two decades.
Applications to refinance surged this week to the highest level in seven months, the Mortgage Bankers Association said.
Anxiety over the European crisis has caused global investors to snap up Treasury bonds, which they view as much safer than other investments. Treasury yields have fallen as a result, taking mortgage rates down, too.
When the crisis eases, and especially if the US economic recovery stays on track, expect investors to move out of bonds and back into stocks. That would make mortgages more expensive.
Associated Press May 28, 2010
Friday, June 4, 2010
APPRAISAL vs ASSESSMENT: Q&A: What Goes into an Appraisal or Assessment?
Judy Leister, an appraiser and co-owner at Northwest Appraisal in Boise, was recently asked a series of general questions about the appraisal industry—mostly regarding residential appraisals—in the Treasure Valley. She provided the following answers:
Q. What is the difference between assessors and appraisers? Do they place different valuations on properties, and why?
A. Assessors and appraisers both value properties. Let’s just deal with real estate properties (the alternatives being personal property and business property, excluding real estate).
Appraisers value properties as of a given date, typically the date they inspected the property, but not always. This can be any day, month, or year (but usually not in the future).
Assessors also value properties, but they do almost all of it as of Jan. 1 of each year.
Appraisers inspect the property, go out and find sales of similar properties to compare to, look at costs to rebuild the property if the property is fairly new and typical; and, if the property provides income, they may consider the value of the income stream.
Assessors use mass valuation techniques (statistical analysis) to raise or lower values of most properties in a given year. This is based on sales prices, overall, of relatively similar homes (properties) in a given geographic area. This is how about 80 percent of properties are assessed.
Occasionally (about every five years) an area will come up for reappraisal. When that happens the appraisers on staff with the County Assessor’s office will go out and look at the outside of the property and perform an appraisal. This sets a value for the property which, in subsequent years, is raised or lowered according to the assessment process described above. The appraisal is always done as of Jan. 1 of the year regardless of when the appraiser looks at the property. (Houses built during a year are an exception.)
There are industry-wide standards for appraisals and every appraisal is expected to meet these standards; however, the client (person for whom the work is done) can call a lot of the shots.
For example, some clients want a very detailed study of what it would cost to rebuild a property, and some don’t. Some clients want all of the comparable properties to be sales within a certain physical radius (say 1/2 mile).
Some clients don’t care about proximity but want you to use similar neighborhoods with homes of the same age. For example, you might compare parts of the North End to certain areas on the Bench.
Fannie Mae, Freddy Mac, FHA, VA and Jumbo loan providers all have different requirements. The county, as the client of the assessor, also has different requirements for its appraisals, so an appraisal for the county could be very different from an appraisal for, say, an FHA loan even if they were both done by qualified appraisers.
But the big difference is date. Most fee appraisals are done and the client gets the results right away. What’s my home worth? The appraiser comes out and inspects and you get the value in about a week.
With the assessor’s office, the appraisal is always done as of Jan. 1 and you get the results in May or June.
This means that if a house just like yours sold in August 2009 for $100,000 but in January the same floor plan in your area sold for $80,000 and in March for $75,000, when you get your assessment in May they won’t be able to use the last two sales because they happened after Jan 1. Your house may be assessed at $100,000. You know that’s wrong because you know what houses in your neighborhood are selling for. And if you don’t look at your assessment until you get your tax bill in November, it’s even worse because now it’s almost a full year later.
Nobody cares when the market is going up (obviously.) But people, being how they are, perceive a great injustice if the market is rapidly falling.
I’ve referred to houses here, but basically I think it all works pretty much the same, except often the appraiser is dealing with income, too.
I think they [assessors] are hampered by an overlying attitude, right from the top down, that everyone is always trying to cheat on their taxes by insisting that their property is worth less than it is. It’s understandable but very annoying and it does predispose them to value higher than may be realistic in a downward trending market.
Q. What is looked at when the appraiser is gauging the value of a home?
A. We look at the tangible and intangible things that give or take value away from a property. In other words, we try to mimic a typical buyer’s reaction.
Here are some of the things we look at:
Were there any sales concessions (did the previous owner also include all the new leather furniture with the purchase or did they pay $10,000 worth of closing costs or prepaid loan fee for the purchaser)?
Was the transaction a normal fee simple deal or was there something else to consider (like, maybe it was a state cottage lease up on Payette Lake and the state will own the land)?
What’s the design of the house? A single level, 2,000-square-foot home might be worth more than, say, a 2,000-square-foot skinny little three-story. Is the floor plan good?
What’s the quality of the construction? What is the wall construction like? Are the windows wood clad or metal? Hardwood floors or vinyl? Formica or slab granite?
What’s the age of the property? Is it 20 years old or new?
What condition is it in? Like-new or trashed? Has it been well maintained?
How many bedrooms, baths, square feet does it have? Does it have a basement? Is the basement finished?
Is there anything strange about it? Is the only bathroom off the kitchen? Is the patio only three feet wide? Is there no room for a normal kitchen or dining room table? In other words, does it work right in its use?
Does the property produce income and how much? And then we adjust for other items that add value in the eyes of a buyer like heating and air conditioning, patios and decks, appliances, hot tubs, fireplaces, fences, landscaping, etc.
Other items are looked at, at the discretion of the appraiser, depending on the type of property.
Q. Along the same lines, do some factors weigh into the overall assessment of the home more than others?
A. Sure—lots of things. A three-car garage versus a single-car garage will typically be given more weight than a hot tub.
Some of the most weighty factors are more intangible—for instance, location. We all know how important that is. Each property is different.
Q. Why do appraisals fluctuate and how is that determined?
A. Supply and demand. Whether we want to believe it or not, our local population is decreasing as people leave to find work elsewhere. This contributes to an oversupply already in place through overbuilding and overdeveloping of lots.
Foreclosures add to the oversupply of properties available for purchase and nothing is worth more than a buyer can find a reasonable substitute for at a lesser price. Given two similar properties, a buyer will usually buy the cheapest.
Q. How and why does the market factor into the appraising process?
A. Property values move up based on increased demand backed up by the power of people to purchase. They move down on the opposite. Right now we have an oversupply and some lack of purchasing power due to unemployment and uncertainty in the economy.
Appraisers can make adjustments for the market moving up or down. If statistics prove that a market is dropping 1 percent per month, for example, an adjustment can be made. Similarly, if the market is going up rapidly, an upwards adjustment can be made to the final value.
Q. On what factors should commercial building valuations be based, in your opinion?
A. Net income for sure and also some of the physical properties which are too numerous and varied to list here. Each property is different. The best rule of thumb is to try to mimic the actions, desires and concerns of qualified buyers in the market for that particular type of property.
If people are picking properties up from banks at half the price it costs to build them or half of what they sold for two years ago, then that is a big factor in the value.
Remember, normally people don’t pay more for something than they can go out and buy a reasonable substitute for. If a significant part of your market is repossessed properties, then that is your market. Deal with it.
Q. Is there less work for appraisers right now, due to the downturn in the economy?
A. Yes. And there will be even less if sales fall off as the first-time homebuyer subsidy ends.
Credit: Gaye Bunderson
(Copyright 2010 Dolan Media Newswires)
(c) 2010 Idaho Business Review, The. Provided by ProQuest LLC. All rights Reserved.
Source: Idaho Business Review, The
Publication date: 2010-05-14
A service of YellowBrix, Inc.
Thursday, June 3, 2010
REMODELING: Cooking Up a Perfect Kitchen
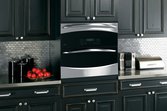
Clutter, distractions, poor work flow—sometimes a kitchen’s layout can hinder the cooking process more than it helps. Decorating can create similar pitfalls. “We get too caught up in color palettes and soft fabrics, and we overthink it,” says Genevieve Gorder, co-host and judge of HGTV’s “Design Star.”
But a well-planned kitchen can boost your cooking experience and make the room an even more treasured space, say Gorder and fellow designers Betsy Burnham (founder of Burnham Design) and Brian Patrick Flynn (founder of DecorDemon.com).
It’s all about focusing.
“A kitchen is the most task-oriented space in the house, so it must honor function as well as aesthetics,” Gorder says. “A light, bright, clean kitchen is a nice framework for the dance that is about to happen, which is cooking.”
How can you re-imagine your kitchen to make it the best possible place to cook?
Think it through
More than any other room, Burnham says, kitchens need to be precisely planned. If you’re remodeling, “you need to go out and really touch and feel all the appliances, see what’s out there,” she says. “It’s not just, ‘This is cool. My friend has this, so I want it.’ It’s, ‘How do I really cook? Where do I put my spoon? Where do I like to have my towels?’ “
Leaf through food magazines to see how professional cooks arrange their kitchens.
“Professional stuff is so available to the public now,” Burnham says. “You can arrange your drawers with those dowels that organize restaurant plates. They’re spring-loaded.”
Installing a second sink or second dishwasher also has become more common.
Big changes don’t have to be expensive, Flynn says. But because a kitchen won’t be remodeled often, “think of how far each dollar goes in relation to durability first, then aesthetics second.”
The designers preach simplicity and timelessness: “Go with classic colors, a classic backsplash,” Burnham says. “You really don’t want a date on that kitchen.”
White’s a good choice
A good way to keep options open and avoid a dated look is to go with white cabinets, says Matthew Gunn, designer and vice president for business development at Classic Kitchens of Virginia in Richmond.
“White cabinets have been popular and will remain popular for many years to come,” he says. “One of the first complaints that I hear when interviewing prospective clients is that their current kitchen is too dark. This can be attributed to dark wood stain, as well as poor lighting.
“Additionally, white cabinets provide design flexibility and allow the designer and homeowner a wider range of choices when considering countertop and tile backsplash color and textures.”
Subscribe to:
Posts (Atom)